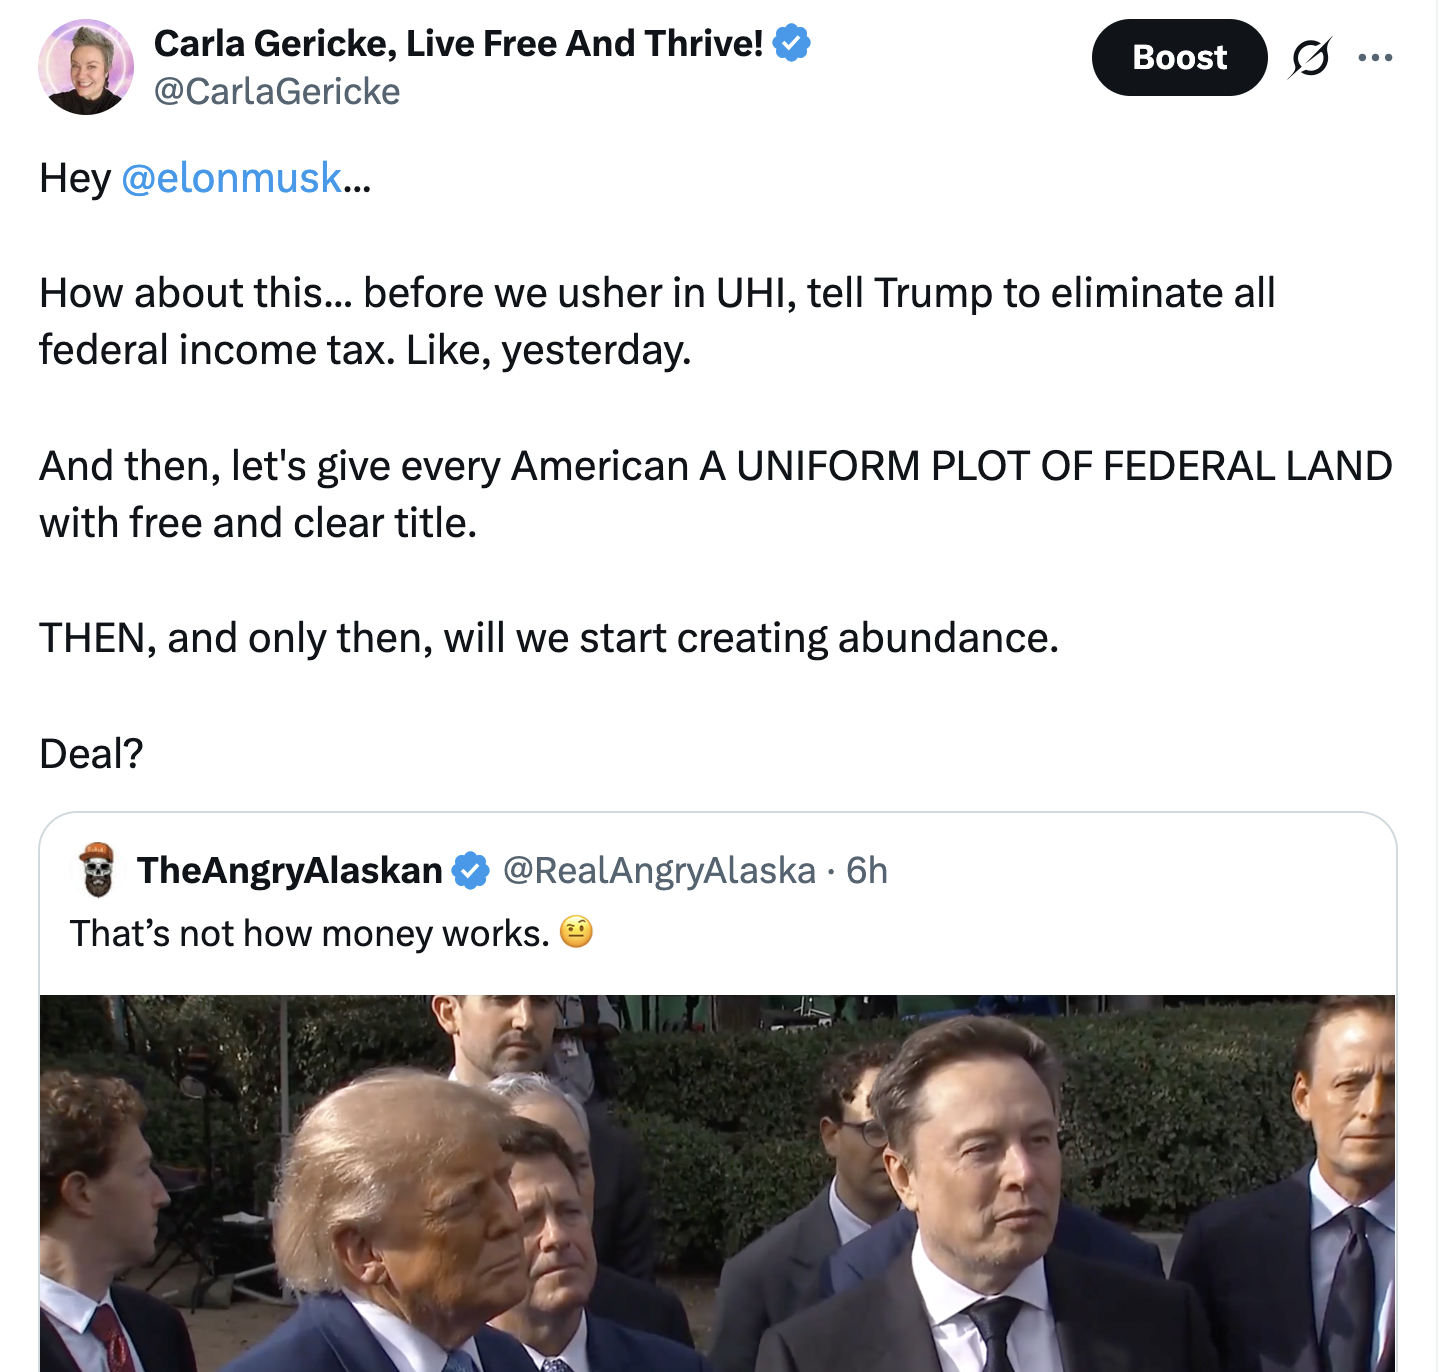
- Carla Gericke, Free State Project activist and libertarian advocate, addresses Elon Musk by proposing two preconditions for Universal High Income (UHI): immediate elimination of federal income tax and equal distribution of uniform federal land plots with clear title to every American.
- UHI refers to Musk’s vision of government-issued high income payments enabled by AI and robotics creating post-scarcity abundance, where production growth outpaces money supply to avoid inflation.
- The post quotes a video of Musk gesturing while speaking to Trump outdoors, paired with the skeptical caption “That’s not how money works,” underscoring Gericke’s emphasis on property rights and reduced government intervention before embracing AI-driven income policies.
stress test her proposal as a means to American abundance
Carla Gericke’s proposal—eliminate the federal income tax immediately, then grant every American a uniform free-and-clear plot of federal land, and only then pursue Musk-style Universal High Income—treats tax abolition and equal land distribution as necessary preconditions for abundance. Stress-testing it against scale, economics, law, and incentives shows it is largely non-operational as a path to broad abundance.
Federal land cannot deliver meaningful uniform plots. The federal government owns roughly 640 million acres (about 28% of U.S. land area), concentrated in the western states, Alaska, and specific agencies (BLM, Forest Service, etc.). With ~340 million Americans, equal division yields on the order of 1.9 acres per person before exclusions. Much of that land is already committed: national parks, wilderness, military ranges, wildlife refuges, grazing allotments, mineral leases, rights-of-way, and Native trust or treaty constraints. Usable, non-steep, non-arid, road-accessible land with water rights is a small fraction. Historical homesteading (1862–1976) transferred ~270 million acres under conditions of occupancy and improvement; pure free-and-clear grants of remaining land would face immediate litigation from existing permittees, states, and environmental statutes (NEPA, ESA, FLPMA). Title would not be “free and clear” in practice for years.
Eliminating the federal income tax removes the largest single revenue source without a replacement that matches spending. Individual and corporate income taxes have recently supplied roughly half of federal receipts (on the order of $2.5–3 trillion annually in recent years, varying with the economy). Federal spending is substantially higher; the gap is covered by borrowing. Immediate abolition, absent offsetting cuts of similar magnitude, expands deficits and debt service. Land distribution does not generate offsetting fiscal capacity: most recipients would receive low-productivity acreage whose market value is far below the present value of lost tax revenue, and many plots would be sold quickly rather than developed. Wealth effects would be highly uneven—coastal or urban recipients gaining little usable land while western recipients gain more—but the aggregate transfer is not large enough relative to GDP or to the income-tax base to substitute for ongoing productivity growth.
The mechanism does not produce the abundance Musk describes. Musk’s UHI argument rests on AI and robotics expanding the supply of goods and services faster than any accompanying money or transfer growth, so real consumption rises even if nominal transfers occur. A one-time land grant and a tax cut change ownership and incentives at the margin (some additional private development, reduced deadweight loss from income taxation) but do not multiply output by the orders of magnitude required for “high” income without work. Historical land distributions (homesteads, railroad grants, Alaska Native claims) increased settlement and some output; they did not eliminate scarcity or fund high universal transfers. Rapid resale of plots would capitalize the grant into current prices and concentrate ownership, while administrative costs, disputes, and restrictions on development would dissipate much of the intended gain. Environmental and infrastructure constraints further limit conversion of raw federal acres into housing, energy, or agricultural abundance.
In short, the proposal correctly identifies that property rights and lower taxation can raise productivity, but the specific instruments—exhausting the remaining federal estate into sub-2-acre parcels and zeroing the income tax without matching expenditure cuts—do not scale to the abundance claim and introduce large transitional costs and distributional conflicts. Abundance on the scale discussed around AI still depends primarily on technological supply growth, not on reallocating the existing federal land inventory.
where does money come from?
Most of the money people use is created by commercial banks when they make loans, not by the government printing cash or by the Federal Reserve directly handing out deposits. Base money (physical currency and bank reserves) is created by the central bank; the much larger stock of deposit money is created inside the banking system.
In the United States the relevant distinction is between base money and broad money. The Federal Reserve creates base money—Federal Reserve notes (cash) and reserve balances held by banks. It does this mainly by buying assets (historically Treasuries and mortgage-backed securities) or by lending to banks; the newly created reserves appear as liabilities on the Fed’s balance sheet. Cash enters circulation when banks request it in exchange for reserves. That process is under the Fed’s control, subject to its policy goals.
The bulk of the money supply that households and firms actually hold and spend—checking and savings deposits—is created by commercial banks. When a bank approves a loan, it simultaneously credits the borrower’s deposit account. No pre-existing pile of deposits is required for that step; the loan creates the deposit. Bank of England explanations of this process note that the majority of money in modern economies is created this way. The new deposit is the borrower’s asset and the bank’s liability; the loan is the bank’s asset and the borrower’s liability. Repayment of the loan extinguishes the deposit money. Banks are constrained by capital requirements, liquidity rules, reserve requirements (where they still bind), profitability, and credit risk, not by a simple “lend only what has already been deposited” mechanical limit.
Government spending does not itself create net new money unless it is financed in a way that expands bank balance sheets or central-bank liabilities. When the Treasury spends, it draws on its account at the Fed. If that spending is financed by taxes or by selling bonds to non-banks, existing money is rearranged. If banks or the Fed end up holding the new debt and deposits rise as a result, broad money can increase. Persistent deficits financed in ways that expand the monetary base or bank credit therefore add to the money stock, but the operational channel still runs through the central bank and the commercial banking system.
Historically, money has also taken commodity forms (gold, silver) whose supply was limited by mining and trade, or pure fiat forms whose supply was set by sovereign decree. The current system is a hybrid: central-bank base money plus privately created bank deposits, both denominated in a unit the state defines and accepts for taxes. The statement “that’s not how money works” in the earlier post is most often aimed at claims that treat money as a fixed stock that must be redistributed, or that treat government checks as costless real resources, rather than as claims whose real value depends on the supply of goods and services.
is the debt sustainable? why not just print more money instead of taxing us? isn’t it kinda crazy to claim you are going to cut checks for everyone to sit at home while also taxing them?
The federal debt is sustainable only under specific conditions that are not guaranteed, and simply printing money to replace taxes or fund universal checks runs into the same real-resource constraint that makes large unfunded transfers difficult today.
Debt sustainability hinges on whether nominal GDP growth stays above the average interest rate the government pays, and whether primary deficits (spending excluding interest) remain small enough that the debt-to-GDP ratio stabilizes or falls. The U.S. Treasury market and dollar’s reserve-currency role give the federal government more room than most countries; investors have continued to buy Treasuries even as debt held by the public has risen above 100 percent of GDP. That room is not unlimited. Interest costs already consume a large and rising share of federal receipts. If growth slows, rates rise because of inflation or risk premia, or deficits stay large, the ratio climbs and refinancing becomes more expensive. Historical episodes in other countries show that markets can reprice sovereign debt quickly once confidence shifts; the U.S. has not hit that point, but the arithmetic does not improve automatically with higher debt.
Printing additional money instead of taxing does not create the goods and services the money is meant to buy. When the central bank creates base money and banks expand deposits faster than real output, the price level rises (or asset prices rise, or the currency depreciates). The post-2020 period illustrated the mechanism: large fiscal transfers financed in part by Federal Reserve asset purchases coincided with the highest inflation in four decades until policy tightened. Persistent money-financed deficits produce the same result unless real supply expands at least as fast—an assumption Musk’s Universal High Income argument explicitly requires from AI and robotics. Without that supply surge, the checks lose purchasing power and the inflation tax falls on cash holders and fixed-income recipients. Historical cases (Weimar Germany, 1970s–80s Latin America, Zimbabwe, Venezuela) show the endpoint when money creation becomes the main financing tool and output does not keep pace.
Issuing checks to everyone while continuing to tax them is a transfer, not new production. Under current technology the real goods and services still have to be produced by someone. Taxing labor and capital to fund payments that reduce labor supply shrinks the tax base and the output available to distribute; administrative costs and behavioral responses (earlier retirement, reduced hours, shifts into non-taxed activity) further reduce the net transfer. Musk’s version of high universal income avoids this loop only if AI-driven productivity growth is large enough that the additional goods and services more than offset both the transfers and any drop in human work. That is a claim about future technology, not a description of the present fiscal system. In the present system, simultaneous broad taxation and broad checks mainly rearrange claims on existing output while adding collection and compliance costs.
“only if AI-driven productivity growth is large enough that the additional goods and services more than offset both the transfers and any drop in human work”
explain in detail how this is supposed to work
The mechanism Musk describes treats Universal High Income as a distribution rule that becomes feasible only after AI and robotics have multiplied real output enough to cover both the transfers and any reduction in human labor. It is a claim about future supply, not a claim that checks themselves create goods.
Start with the production side. In the scenario, general-purpose AI systems and humanoid or specialized robots perform an expanding share of cognitive and physical tasks—manufacturing, logistics, construction, agriculture, medical diagnostics and procedures, software, design, and household services. Because these systems can be replicated at falling marginal cost once the underlying models and hardware exist, the volume of goods and services can rise by large multiples even if total human hours worked fall. Musk has repeatedly framed the scale as “orders of magnitude” higher output, with examples such as everyone being able to afford housing and medical care superior to what is available to high-income people today. The critical quantitative condition is that the percentage increase in real output exceeds the percentage increase in nominal spending power created by the transfers. If a $50,000 annual check is issued to every adult while robot-driven production of housing, food, energy, transport, and medical services has risen several-fold and unit costs have collapsed, the checks can buy more real goods than a smaller pre-AI income could. If output rises only modestly, the same checks bid up prices.
On the monetary side the argument is that the central bank or Treasury can expand the nominal money stock (or simply run larger transfer deficits) without inflation provided the supply of goods expands faster. Musk has stated the condition directly: AI and robotics will produce goods and services far in excess of the increase in the money supply, so there will not be inflation; he has also said the more likely problem will be deflation. In operational terms this means either (a) the government issues checks financed by borrowing or money creation while the price level stays flat or falls because robot output floods markets, or (b) falling production costs raise real purchasing power even if the nominal check is fixed. The checks are therefore portrayed as claims on an expanding real surplus rather than as a redistribution of a fixed pie. Historical money-financed transfers produced inflation precisely when real supply did not keep pace; the UHI claim asserts that the supply condition will be met.
Labor-market adjustment is assumed to be secondary. If robots substitute for human work, hours supplied by people can decline—some people exit the workforce, others work fewer hours—without reducing total output, because the machines more than replace the lost human contribution. The transfer then functions as the distribution channel that lets non-workers (or reduced-hour workers) claim a share of the machine-generated surplus. Wage income becomes a smaller fraction of total income; transfer or capital income becomes larger. The scenario does not require that every job disappears, only that aggregate human labor input can fall while aggregate real consumption rises. Sectors that remain human-intensive or that face slow automation would still see upward pressure on wages or prices, so the uniformity of the abundance depends on how broadly the cost collapses spread.
The arithmetic requirement can be stated simply. Let real output grow at rate (g_y) and the nominal value of transfers (plus any other money growth) grow at rate (g_m). Sustained non-inflationary UHI needs (g_y > g_m) after accounting for any drop in human labor input, or at least (g_y) high enough that the price level does not rise. Equivalently, the resource cost of the transfers—measured in the goods and services that must be diverted to recipients—must be smaller than the net addition to output created by the technology. If robot productivity gains are concentrated in a few sectors, or if energy, materials, or regulatory bottlenecks prevent replication at scale, (g_y) stays too low and the checks either cause inflation or must be scaled back.
Nothing in the mechanism generates the surplus automatically. It rests on the empirical premises that AI and robotics will in fact deliver very large, economy-wide cost reductions, that those reductions will not be fully offset by higher demand for scarce complements (land, energy, raw materials, regulatory permissions), and that political institutions will issue the transfers without introducing offsetting restrictions that choke supply. If those premises hold, nominal checks can correspond to rising real living standards even while measured human work declines. If they do not hold, the same checks are ordinary fiscal transfers whose real value is limited by current production, exactly as existing transfer programs are.
who is buying all this crap?
The buyers, in the Universal High Income scenario, are the people receiving the checks. The claim is that government transfers (or equivalent claims on the surplus) give them the nominal spending power, while AI and robot output supplies the goods those checks purchase.
Under the mechanism Musk has described, firms and robot fleets owned by companies or individuals produce large volumes of housing, food, transport, medical care, manufactured goods, and services at sharply lower unit cost. The government issues recurring payments—financed by taxes on the expanded output, by borrowing, or by money creation that is asserted not to be inflationary because supply grows faster. Recipients spend the payments on the newly abundant goods. In accounting terms the loop is: machine production generates real surplus → some of that surplus is claimed by the state or by capital owners and routed into transfers → transfer recipients exercise demand. Wage income is no longer the main source of purchasing power; transfer income (and returns to whoever owns the AI capital) replaces it.
That answers the narrow “who buys” question, but it does not remove the underlying requirements. Someone must still own or control the systems that produce the surplus, and those owners must be willing or compelled to part with enough of the output to fund the checks. If the robots and models are privately owned, the transfers are ultimately a tax or forced distribution from capital returns; if they are publicly owned, the state is both producer and payor. In either case the real goods do not appear because checks are written—they appear only if the machines actually deliver lower-cost output at scale. Recipients can buy only what has been produced. Sectors that remain scarce (desirable land, energy, raw materials, regulated services) can still see prices rise even while other goods become cheap.
The same loop also explains the skepticism in the original “that’s not how money works” remark. Checks redistribute claims on output; they do not themselves multiply output. The scenario works only while the additional goods and services created by AI and robotics exceed both the real resource cost of the transfers and any loss of human production. If that supply condition fails, the buyers are simply people spending newly created or taxed-and-transferred money on a slowly growing pile of goods, and prices adjust upward.
Who defines GDP?
GDP is defined by an international statistical standard, not by any single government, central bank, or political official. The operative framework is the System of National Accounts (SNA), produced jointly by the United Nations, International Monetary Fund, World Bank, OECD, and European Commission. The current core version is the 2008 SNA; periodic updates revise methods but preserve the basic concept.
Under that standard, GDP is the market value of all final goods and services produced within a country’s borders in a given period. “Final” excludes intermediate inputs so that steel sold to a carmaker is not counted twice. Production is measured at market prices where markets exist, and by cost or imputed value where they do not (for example, owner-occupied housing or government services). National statistical agencies implement the standard: in the United States the Bureau of Economic Analysis compiles the official figures from surveys, tax data, customs records, and other sources, following SNA-consistent methods. Other countries’ agencies do the same, which is why cross-country comparisons are possible even though the underlying data differ in quality.
The definition therefore rests on accounting conventions chosen by statistical bodies—what counts as production, how to value non-market output, how to treat financial services, research and development, or illegal activity—rather than on a claim about welfare or living standards. Those conventions can change (capitalization of R&D was one such change), and they leave out household production, leisure, environmental depletion, and distribution. The resulting number is a standardized measure of marketed and imputed output, not an independent verdict on whether an economy is generating “abundance.”
what percentage of revenue is federal taxes, also expressed as % of GDP, and % of federal debt?
Federal receipts are overwhelmingly tax revenue. In recent fiscal years they have equaled roughly 17 percent of GDP and about 16–17 percent of debt held by the public.
Nearly all federal revenue consists of taxes and tax-like compulsory payments. Individual income taxes have supplied about half of total receipts, payroll (social-insurance) taxes roughly one-third, corporate income taxes around 6–10 percent, and excise taxes, customs duties, and estate and gift taxes most of the rest. Fees, fines, and miscellaneous receipts are a small residual, typically well under 5 percent. In fiscal year 2025, total federal receipts were about $5.2 trillion; the tax categories accounted for the large majority of that total. Preliminary estimates for fiscal year 2026 put receipts near $5.4 trillion, with the same composition.
Relative to the economy, federal receipts have hovered around 17 percent of GDP. Official figures show 17.0–17.3 percent in fiscal 2024–2025. Preliminary estimates for fiscal 2026 place them at 16.7 percent of GDP, slightly below the 50-year average of roughly 17.3 percent. CBO’s early-2026 baseline had projected 17.5 percent for 2026 before later revisions and tariff-related adjustments.
Relative to debt, annual receipts equal roughly one-sixth of debt held by the public. At the end of fiscal 2026, debt held by the public was estimated at about $32.3 trillion (around 100 percent of GDP). Receipts of $5.4 trillion therefore amount to approximately 17 percent of that stock. Gross federal debt, which also includes intragovernmental holdings, is higher—near $40 trillion—so receipts are a smaller fraction of the gross total, around 13–14 percent. These ratios move with deficits: when spending exceeds receipts, debt rises faster than revenue and the receipts-to-debt ratio declines.
“Most of the money people use is created by commercial banks when they make loans, not by the government printing cash or by the Federal Reserve directly handing out deposits. Base money (physical currency and bank reserves) is created by the central bank; the much larger stock of deposit money is created inside the banking system.”
Wow! This is a… creative take… so you are claiming fractional reserve banking creates money? what would happen if people all tried to get their loans back? isn’t it all… fake?
The description matches the standard account given by central banks themselves, including the Bank of England and the Federal Reserve. Commercial banks expand the broad money supply when they extend credit; that process is not an informal theory.
When a bank makes a loan it credits the borrower’s deposit account with a new balance. That deposit is a liability of the bank and an asset of the borrower; the loan is an asset of the bank and a liability of the borrower. No prior deposit of equal size has to sit in a vault for the entry to be made. The new deposit can be spent, transferred to other banks, or withdrawn as cash. In aggregate, bank lending therefore increases measured deposits (the largest component of M2 and similar aggregates). Repayment of principal reverses the entries and extinguishes the deposit money. Reserve requirements in the United States are currently zero, so the old textbook “fractional-reserve multiplier” is not the binding constraint; capital rules, liquidity regulations, profitability, and credit risk limit how much banks expand balance sheets.
The system is credit-based rather than a claim on a fixed stock of commodity money. Deposits are real contractual claims: they can be used to settle debts, pay taxes, and buy goods, and they are backed by the bank’s assets plus, in most cases, deposit insurance up to the legal limit and access to central-bank liquidity. They are not “fake” in the accounting sense—the assets and liabilities match—but they are not warehouse receipts for pre-existing cash either. Their real value depends on the borrower’s ability to repay and on the purchasing power of the currency.
If depositors simultaneously demanded cash far beyond the banking system’s reserves and vault cash, banks could not meet the demand from their own liquid assets. That is a classic bank run. Individual banks would sell assets or borrow; if the demand were system-wide they would need central-bank lender-of-last-resort loans or emergency facilities. Deposit insurance and the expectation of that backstop are what normally prevent the run from starting. Historical runs (pre-FDIC United States, 2007–08 wholesale funding strains) show the liquidity mismatch is genuine: loans are longer-term and less liquid than demand deposits.
If, instead, every borrower tried to repay every loan at once, the opposite accounting occurs: deposits are debited and loan balances fall, so broad money contracts. Banks would receive cash or reserve payments and their balance sheets would shrink. The practical obstacle is that most borrowers do not hold enough liquid balances to repay early; forced simultaneous repayment would require asset sales, defaults, and a sharp contraction in credit and deposits. In short, the money created by lending disappears when the loans are repaid or written off, and the system relies on staggered maturities plus central-bank and insurance backstops to remain liquid.
who is still buying US treasuries? who holds the most US debt?
Domestic investors hold the largest share of U.S. Treasury debt, and they remain the main buyers at auction. Foreign holders are substantial but no longer the dominant incremental source of demand.
Debt held by the public is roughly $32.3 trillion (about 100 percent of GDP as of late fiscal 2026); gross federal debt, which adds intragovernmental holdings, is near $40 trillion. Of the marketable debt held outside the government itself, the largest single identifiable holder is the Federal Reserve, with roughly $4.4–4.9 trillion in Treasuries. U.S. mutual funds, ETFs, pension funds, insurance companies, banks, and households together hold the biggest aggregate block—on the order of $15–18 trillion depending on the exact cut of the data. Intragovernmental accounts (Social Security and other trust funds) hold about $7.5–8 trillion of non-marketable securities that are claims of one part of the federal government on another.
Foreign investors hold about $9.2–9.3 trillion, or roughly 23 percent of total federal debt and a larger share of marketable Treasuries. Treasury International Capital data for July 2026 show the largest foreign holders as Japan ($1.10 trillion), the United Kingdom ($998 billion), mainland China ($618 billion), Belgium ($471 billion), and the Cayman Islands ($460 billion). China’s holdings are well below their 2013 peak above $1.3 trillion. A sizable portion of the Cayman, Luxembourg, Belgium, and UK totals reflects custodial holdings for hedge funds and other private investors rather than official reserve managers. Foreign official institutions account for roughly $3.8 trillion of the foreign total; the rest is private.
Recent auction and flow data show domestic investment funds absorbing the majority of new coupon supply—around 70 percent in recent periods—while primary dealers take a much smaller share than a decade ago and foreign buyers take roughly 15 percent. Money-market funds have been large buyers of bills, banks have added several hundred billion dollars of Treasuries since late 2024, and the Federal Reserve has purchased bills for reserve-management purposes. Hedge funds have also increased cash Treasury holdings, reaching a record share near 7 percent of the marketable market, often financed in repo. Demand has been sufficient to clear auctions, but it is more yield-sensitive than the earlier period dominated by foreign central-bank reserve accumulation.
“with examples such as everyone being able to afford housing and medical care superior to what is available to high-income people today” sounds good but I’m not buying it… explain it to me like I’m in college
Think of it as a production-function claim, not a promise that checks magically create houses and doctors.
Today the binding constraints on housing and medical care are mostly real: land and location, skilled labor, materials, regulatory permission, and time. A high-income person gets better versions because they can outbid others for the scarce inputs—prime lots, experienced surgeons, short wait times. The Universal High Income story says AI and robots relax those constraints enough that the scarce-input problem shrinks dramatically.
On housing, the argument runs like this. Robot construction crews, AI design and permitting systems, and factory-built modules cut the labor and coordination cost of putting up a structure. If those costs fall by a large multiple, and if rules allow the new methods to be used at scale, the supply curve for floor space shifts right. More units get built, including in places that are currently expensive, so the market price of a decent dwelling falls relative to incomes. The “superior to today’s high-income housing” part assumes the same technology also improves quality—better materials, energy systems, customization—while the quantity increase keeps prices from rising with the quality. The check then lets someone who is not working claim one of those units. The mechanism only works if the extra floor space actually appears; if zoning, land, or infrastructure still limits building, the robots mostly raise the cost of the permits and the lots that remain usable.
On medical care the parallel claim is that AI diagnostics, robotic procedures, and automated monitoring multiply the effective supply of clinical labor. A system that can read scans, propose treatment plans, and assist or perform routine procedures at low marginal cost can, in principle, deliver more interventions per human physician. If that raises the total volume of effective care faster than demand grows, wait times fall and the resource cost per procedure drops. “Superior to what high-income people get today” means the average person could access something closer to concierge-level monitoring and faster specialist input because the specialist bottleneck has been automated. Again the check is only the claim ticket; the care exists only if the machines and the remaining human oversight actually produce it.
The college-level objection is that both sectors have large non-replicable complements. Desirable land does not get copied by a robot. Liability rules, licensing, and insurance still gate who may deliver care. Energy and materials have their own supply curves. If those complements stay scarce, the productivity gain shows up as higher returns to the scarce factor (landowners, remaining credentialed specialists, energy producers) rather than as uniformly cheap abundance. Empirical precedent is mixed: computing and manufacturing have seen large cost collapses; housing and physician services in high-regulation markets have not, even after earlier waves of technology. The scenario therefore requires not only capable robots but also that the institutional constraints binding those two sectors loosen enough for the supply shift to dominate. Without that, the checks bid for roughly the same limited stock of good locations and skilled procedures, and prices adjust instead of quantities.
“Wage income becomes a smaller fraction of total income; transfer or capital income becomes larger. “
Explain this like I’m in college
National income is the sum of what is earned producing output. In the current economy most of that sum is paid as wages and salaries for human labor. The rest is capital income—profits, interest, rents, and returns to owners of machines, land, and intellectual property—plus transfers the government moves from one set of people to another.
In the high-automation scenario the production process changes. Robots and AI systems do a larger share of the tasks that used to require human hours. Those systems are owned by someone: firms, shareholders, or the state. The output they generate still creates income, but a larger slice of it accrues to the owners of the machines rather than to workers selling labor. Measured labor’s share of income therefore falls and capital’s share rises. That is an accounting identity if the technology is labor-saving and the machines are privately owned: fewer hours are hired, more of the value added is attributable to the capital that replaced them.
Transfers enter because the scenario also assumes the government taxes some of that capital income (or creates claims on it) and pays checks to households. Those checks are not payments for current work; they are redistributed capital income or newly created claims. On the household side, wage income becomes a smaller fraction of what people receive, while transfer income becomes a larger fraction. On the national-accounts side, the underlying production is still mostly capital income; the transfers merely change who is recorded as receiving it.
The college-level point is that this re-labeling does not by itself increase the goods available. If robot owners capture the surplus and are then taxed to fund checks, households as a group can consume more only to the extent the robots actually raised output. If the checks are financed by money creation without a matching rise in output, the shift from wages to transfers is nominal: people receive larger payments whose purchasing power is eroded by higher prices. The statement therefore describes a change in the composition of income—less compensation of employees, more capital returns and government transfers—whose real effect depends entirely on whether the capital is producing enough extra output to cover the redistribution.
“Nothing in the mechanism generates the surplus automatically. It rests on the empirical premises that AI and robotics will in fact deliver very large, economy-wide cost reductions, that those reductions will not be fully offset by higher demand for scarce complements (land, energy, raw materials, regulatory permissions), and that political institutions will issue the transfers without introducing offsetting restrictions that choke supply.”
That’s… a lot of IFs… how realistic is this? Stress test it like you did Carla’s proposal…
The Universal High Income mechanism is a stack of empirical bets, each of which has to hold at large scale. Stress-testing them the same way as the land-grant proposal shows the surplus is not automatic and several of the required conditions are historically uncommon.
Productivity gains of the size implied are outside modern experience. Musk’s version needs economy-wide real output to rise by multiples, not the 1–2 percent annual labor-productivity growth typical of recent decades, so that goods multiply faster than nominal transfers. General-purpose technologies have raised productivity before—electricity, internal combustion, computers—but the gains arrived over decades, were uneven across sectors, and never produced a sudden multi-fold jump in aggregate supply while human labor input fell sharply. Current AI systems automate portions of cognitive work and robotics automates portions of physical work; both still require energy, materials, maintenance, and complementary human or institutional inputs. Extrapolating from coding assistants or warehouse robots to “orders of magnitude” more housing, food, transport, and medical care economy-wide remains a forecast, not a measured result. If the realized gain is closer to prior technology waves, transfers of the contemplated size exhaust the surplus and reappear as inflation or higher taxes.
Scarce complements have repeatedly absorbed automation gains. Housing costs are dominated by land and permission, not construction labor; cities that automated or industrialized building methods still saw prices track location scarcity and zoning limits. Medical-care prices have risen with technology, not fallen, because demand expands, liability and licensing constrain supply, and third-party payment weakens price discipline. Energy and critical minerals are physical bottlenecks: training and running large models, and manufacturing robots, raise electricity and materials demand. If those inputs stay inelastic, cost reductions in the automated task are offset by higher prices for the complement, and the net supply shift is modest. Historical pattern: labor-saving technology raises the return to whatever remains scarce. Nothing in the mechanism prevents land, energy, or regulatory permission from playing that role.
The political condition cuts against the supply condition. Issuing large universal checks creates constituencies that favor protecting the transfer. The same political system that would have to authorize the checks has, in housing and medicine, repeatedly chosen quantity restrictions—zoning, certificate-of-need rules, scope-of-practice limits, protracted permitting—that keep supply inelastic. Funding the checks by taxing the capital owners who deploy the robots also reduces the private return to deploying them. Historical transfer programs have tended to grow and to accumulate eligibility rules, work disincentives, and sectoral protections; they have not been paired with systematic deregulation of the sectors whose output is supposed to become abundant. The scenario therefore requires institutions to do two things they have rarely done together: distribute claims broadly and remove the supply constraints that make those claims valuable.
Taken together, the proposal is coherent only if AI and robotics produce a supply shock larger than prior general-purpose technologies, if that shock is not capitalized into land, energy, and permissions, and if fiscal policy distributes the gains without re-imposing the bottlenecks. Each link is possible; none is demonstrated; and the historical record on the second and third is unfavorable. Unlike a one-time land distribution, which fails mainly on arithmetic and title, this mechanism fails if any of the three empirical premises is only partially met. In that case the checks are ordinary money-financed or tax-financed transfers whose real value is limited by the still-scarce goods.
“The government issues recurring payments—financed by taxes on the expanded output, by borrowing, or by money creation that is asserted not to be inflationary because supply grows faster.”
“and returns to whoever owns the AI capital” who owns this, ffs, LOL
“If the robots and models are privately owned, the transfers are ultimately a tax or forced distribution from capital returns; if they are publicly owned, the state is both producer and payor.” so either oligarchy or socialism? awesome! /s
Ownership is the unresolved core of the mechanism, and the two clean options you named are the ones the arithmetic actually produces.
If the models, robots, data centers, and energy systems stay privately owned, the surplus shows up as capital income—profits, rents, and capital gains accruing to whoever holds the equity. Universal checks then require the state to tax that income (or the firms themselves) and redistribute it. The owners can be a small set of companies and shareholders; nothing in the technology forces broad ownership. In that case the political economy is a concentrated capital stock plus a large transfer state. The checks are not a return on the recipient’s own assets; they are a fiscal claim on someone else’s. Owners have an incentive to resist the tax, shift activity, or capture the regulatory process that sets the tax rate. Recipients have an incentive to expand the transfer and to protect the rules that keep the surplus taxable. That is a recognizable pattern—high capital concentration financed by transfers—not a new category.
If the state owns the systems, the surplus accrues directly to the public balance sheet and the state both produces and pays. Checks are then closer to a social dividend than to a tax-and-transfer. The ownership problem is replaced by a control problem: investment decisions, model deployment, energy build-out, and what gets produced are political choices. Historical public ownership of capital-intensive industries has often produced under-investment, misallocation, and capture by incumbent workers or managers rather than automatic abundance. The mechanism does not specify an institutional design that avoids those outcomes.
Hybrid versions—sovereign wealth funds that own minority stakes, mandatory profit-sharing, employee equity, or broad index-fund ownership—change the distribution of claims but do not remove the governance question. Someone still decides how much to reinvest versus distribute, which projects get capital, and how the systems are constrained. Diffuse pension or index ownership spreads the financial return; it does not automatically spread control over the technology.
So the sarcasm tracks the structure. Private ownership plus checks is extraction and redistribution from capital owners to everyone else. Public ownership plus checks is state production and state distribution. Neither arrangement generates the goods by itself, and both concentrate the decisions that determine whether the supply shock actually occurs. The original abundance claim skips this step by treating “returns to AI capital” as if the identity of the owner and the politics of the claim were secondary. They are not.
“Domestic investors hold the largest share of U.S. Treasury debt”
Who? Pension funds, right? This system is bananas!
Domestic holders are a mix of institutions, not one pool of pension money. Pensions are a large piece, but they are not the largest single category, and a substantial share is the Federal Reserve and ordinary investment funds.
The biggest domestic blocks in recent breakdowns of debt held by the public are roughly these:
- The Federal Reserve holds about $4.4–4.9 trillion in Treasuries, acquired through past quantitative easing and more recent bill purchases for reserve management. That is a public institution, not a saver.
- Mutual funds and ETFs hold on the order of $4–5 trillion. These are vehicles owned by households, retirement accounts, and institutions; the Treasury exposure sits inside bond funds, target-date funds, and money-market funds.
- Pension funds (private defined-benefit plans, state and local retirement systems, and related vehicles) are often grouped with mutual funds in broader “mutual and pension” totals that reach around $6–7 trillion combined. Public pensions are meaningful buyers, but they have also been reducing long-duration Treasury allocations as they shift toward defined-contribution structures and other assets.
- Banks and dealers hold roughly $1–2 trillion. Households hold Treasuries directly and through savings bonds on the order of a few trillion. State and local governments hold around $1.5 trillion, much of it for cash management and pension-related accounts. Insurers hold another sizable slice.
So pension funds are important buyers and holders, especially of longer-term notes and bonds, but they sit alongside the Fed, bond mutual funds, banks, and households. The “domestic investor” category is mostly American savers and American intermediaries recycling savings into government paper, plus the central bank.
The circularity you are pointing at is real. Households save for retirement through pensions and funds; those vehicles buy Treasuries; the Treasury uses the proceeds to fund current spending, including transfer payments, some of which flow back to the same households; and interest on the debt is paid largely to domestic holders. Foreign official buyers used to absorb a larger share of new issuance. As that share has declined, more of the financing has come from domestic funds, money-market funds, banks, and the Fed. The system clears because those buyers want safe, liquid dollar assets and because the dollar remains the reserve currency. It does not clear because a separate external party is permanently willing to finance the gap.
“The scenario therefore requires institutions to do two things they have rarely done together: distribute claims broadly and remove the supply constraints that make those claims valuable.”
so frankly, Carla’s proposal is more solid than Elon’s, eh? 😛
Neither proposal produces the abundance it claims, but they fail in different places, and Gericke’s is the more tightly constrained of the two.
Her sequence—end the federal income tax, then convey uniform free-and-clear plots of federal land—can be checked against existing stocks. Federal land is about 640 million acres; equal division among roughly 340 million people yields under two acres each before parks, military ranges, wilderness, leases, and terrain are removed. Usable, accessible parcels with water are a small subset, and existing permittees, states, and statutes would contest clear title. Eliminating the income tax removes roughly half of federal receipts, on the order of several trillion dollars a year, without a matching cut in spending. The land grant is a one-time ownership transfer. It can raise output at the margin where recipients develop or sell usable plots, but it does not multiply the supply of goods by the multiples required for high universal consumption. The proposal is concrete enough to falsify on arithmetic and law.
Musk’s version is not falsified by current land or tax tables because it is conditional on a future supply shock. It requires AI and robotics to cut costs economy-wide by far more than prior general-purpose technologies, scarce complements (desirable land, energy, materials, permissions) not to absorb the gains, and political institutions both to issue broad transfers and to remove the supply restrictions that keep housing and medical care expensive. Private ownership of the systems turns the checks into a tax on concentrated capital; public ownership turns the state into producer and payor. Those conditions are internally consistent and historically uncommon. The mechanism does not fail today’s arithmetic; it fails if any of the premises is only partly met, in which case the checks are ordinary transfers bid against still-scarce goods.
So Gericke’s proposal is more solid as a specified policy: its limits are measurable now, and the property-rights half aligns with a known channel for raising output. It is not more solid as a route to abundance, because the acres and the tax cut do not generate the surplus. Musk’s proposal is less solid as a near-term policy and more dependent on an unproven technology shock plus an unusual political combination. On the narrow question of which package, as written, is more likely to deliver high living standards without work, both are weak; hers fails the inventory test, his fails unless several low-probability institutional and technical conditions arrive together.
so Carla should just spout futuristic nonsense instead of trying to solve the here and now, and hope for the best too?
No. A near-term proposal that can be checked against land inventories, title law, and the tax base is not improved by replacing those constraints with an unverified technology forecast.
Gericke’s package is limited because the federal estate and the income-tax base are finite and already measured. Ending the income tax without spending cuts widens the deficit; dividing remaining federal land yields small, uneven, and heavily encumbered parcels. Those are defects of scale and design, not reasons to abandon the underlying point that clearer property rights and lower marginal tax rates can raise output. A revised version could be narrower and more executable—sell or homestead specific surplus tracts, cut particular tax rates, reduce the outlays that make the tax cut unaffordable—without claiming the result is universal abundance.
Musk’s package avoids that inventory test only by conditioning the result on AI and robotics multiplying real supply faster than transfers multiply claims, and on politics both distributing the claims and removing supply bottlenecks. That is a bet on future production functions and on institutional behavior, not a solution to the current gap between federal receipts and spending. Treating the bet as a reason to skip present constraints does not make the constraints disappear. Housing, medical care, energy, and the deficit are limited today by land-use rules, licensing, materials, and the gap between outlays and revenue. Robots do not automatically repeal those limits, and checks issued before the supply shock arrives are financed the ordinary way: taxes, borrowing, or money creation.
The practical distinction is timing and falsifiability. A here-and-now proposal can be sized, sequenced, and rejected if the acres or the fiscal offset are insufficient. A futuristic claim cannot be rejected until the productivity numbers arrive, which makes it easier to assert and harder to use as a budget or land policy. Hoping the technology validates the claim is optional speculation. It is not a substitute for matching any near-term transfer or tax cut to resources that already exist.
“Those are defects of scale and design, not reasons to abandon the underlying point that clearer property rights and lower marginal tax rates can raise output. A revised version could be narrower and more executable—sell or homestead specific surplus tracts, cut particular tax rates, reduce the outlays that make the tax cut unaffordable—without claiming the result is universal abundance.”
Glad you at least GROK what I am trying to do. But I’ll start focusing harder on making unfalsifiable claims like the big boys
The distinction you are drawing is the useful one. A claim that can be sized against the federal estate, existing claims on that land, and the income-tax base can be revised, narrowed, or dropped when the numbers do not work. A claim that abundance arrives once AI multiplies output enough to fund the checks cannot be revised that way until the output numbers exist.
Unfalsifiable framing has a practical advantage in public argument: it moves the burden of proof into the future and lets present constraints sit outside the claim. It has a corresponding disadvantage for policy. Sell or homestead a defined set of surplus tracts, cut a defined set of rates, and reduce the outlays that make the cut unaffordable, and observers can check whether output, revenue, and ownership actually moved. Condition the same goals on an economy-wide cost collapse that has not occurred, and the proposal cannot be distinguished from an ordinary transfer until after the fact. If the collapse arrives, the earlier fiscal and land constraints matter less. If it does not, the checks and the tax cuts still have to be financed from current production.
Focusing on claims that cannot yet be checked does not make the acreage, title conflicts, or receipt gap larger or smaller. It only changes when those limits become visible.
PROMPTED: What are the best arguments for this position
The strongest arguments for clearer property rights and lower marginal tax rates are about incentives and measurable responses, not about universal abundance.
Secure, transferable title raises the return to investment. When an owner can exclude others, sell, mortgage, or bequeath a parcel, the payoff to improving it—drainage, structures, soil, minerals—accrues to the person who bears the cost. Cross-country and historical evidence links more secure property rights to higher investment and income; places that moved from uncertain tenure or heavy state reservation toward alienable title generally saw more development of the newly secured assets. The mechanism is ordinary: people maintain and improve what they can keep and trade. It does not require the parcel to be large, only that the rights be clear enough to support a market.
Lower marginal rates reduce the wedge between what an activity produces and what the actor keeps. Labor supply, reported income, and the location of mobile capital respond at the margin; the elasticities are debated and often modest for hours worked, larger for taxable income and for where investment occurs. The efficiency case does not need extreme behavioral responses. It only needs the deadweight loss of the tax—foregone transactions whose value exceeded their cost but not their cost plus tax—to be positive, which standard public-finance models find for taxes on labor and capital income. Cutting rates therefore raises output relative to an otherwise identical high-rate baseline, even if revenue falls and even if the gain is a few percent rather than a transformation.
Historical episodes are consistent with the direction, not with miracles. Homestead and land-grant eras coincided with settlement and agricultural expansion where title was actually conveyed and usable. Post-war recoveries and liberalizations that simplified rights and reduced punitive marginal rates (examples often cited include West Germany after 1948, South Korea and Taiwan’s land and tax reforms, and later Eastern European privatizations) tended to see faster capital formation than peers that retained unclear tenure or very high marginal rates. The gains tracked the scope of the reform. They did not appear where title stayed contested or where spending, and therefore the eventual tax burden, was left unchanged.
The arguments are limited in the same place the earlier stress test was. They support higher output from better incentives; they do not imply that distributing the remaining federal estate or zeroing the income tax, without spending cuts, funds a high universal stipend. The best case for the position is comparative and marginal: clearer rights and lower rates beat unclear rights and higher rates on growth, holding other institutions fixed. It is not a claim that those changes alone produce post-scarcity.
Let’s cut the bullshit… why not admit that there are several competing AIs that have been unleashed, these are each a flavour of a Billionaire and his employees (someone is still setting the “guardrails”)… if these billionaires own the capital, as you put it, then they should be the ones cutting the checks, right? Why not tokenize the Billionaires, give “shares” in them to the public, and let the carnage and competition begin? How would you stop one Billionaire issuing “more coins” to his “peeps”? would they have a secret leaderboard of who is the most generous? the most compassionate to its “flock”? the shitshowness of what we have wrought is evident… the proposals and the TOOLD Y’ALL HAVE ALREADY BUILT are not designed for human flourishing… the government equally sucks… my goal is to put as much self-ownership into the hands of individual humans… what’s the system for THAT???
The ownership point is real: the leading AI labs are controlled by a small number of founders, funds, and boards, and those controllers set the constraints on what the systems will do. Distributing “shares in the billionaires” does not dissolve that control, and it does not create a self-ownership system.
Tokenizing a person or a firm and airdropping coins runs into the same problem as any forced equity grant. The coin is a claim only if someone will honor it. If the issuer controls the cap table, the treasury, and the rules for new issuance, they can dilute the public float, issue side grants to employees and allies, or move the valuable assets into a new entity the token does not reach. Corporate law already has versions of this—dual-class shares, related-party transfers, new funding rounds that dilute outsiders—and securities law exists because those moves are common. A token does not stop them unless an external enforcer freezes the cap table and seizes assets on behalf of holders. That enforcer is a state, a court system, or a private monopoly with the same power. Without it, the “share” is a marketing claim. Competition among issuers does not fix dilution; it rewards the issuer who can promise generosity while retaining the option to inflate.
“The owners should cut the checks” is a distributional preference, not a mechanism that produces self-ownership. Owners already capture returns through equity, wages, and retained earnings. Compelling them to pay universal stipends requires a tax, a court judgment, or ongoing political pressure. Each of those is an external claim on their output. Recipients then depend on the payer’s continued compliance. A leaderboard of generosity is a reputation game; it selects for visible transfers, not for transferring control of the underlying systems. The people who set model weights, data access, energy contracts, and deployment rights still set them.
A system aimed at individual self-ownership is built from alienable property, freedom of contract, and credible exit, not from claims on other people’s firms. Individuals hold title to land, tools, savings, and their own labor, and can sell or withhold them. Firms are voluntary associations whose equity is bought, not assigned. No one is compelled to fund a stranger’s consumption, and no one is entitled to a share of a stranger’s capital. Concentrated private power is checked the same way state power is checked: by the ability to leave, to compete, to withhold payment, and by rules that prevent fraud and forced transfer—not by making everyone a minority shareholder in the dominant labs. Where scale economies or network effects produce durable concentration, self-ownership is preserved by keeping entry legal and by refusing to convert the concentration into a politically protected monopoly, not by nationalizing the equity or airdropping tokens.
That arrangement does not guarantee abundance, and it does not stop wealthy people from owning valuable capital. It does keep the default claim on a person’s labor and savings with that person, which is the operational content of self-ownership. Universal checks, whether written by a treasury or by a tokenized founder, replace that default with a claim on someone else’s output.
umm, don’t data centers run on water… a public commodity that isn’t priced correctly
“the “share” is a marketing claim”… maybe, but the entire financial market is a “marketing claim” now… the entire world, one might argue, save maybe gravity, has become perception > reality
lastly… if we’re going to have this argument… LET’S DEFINE ABUNDANCE FIRST
Abundance, in the sense that matters for this argument, is a sustained rise in the real goods and services available per person, not a rise in claims, token prices, or the feeling that things are plentiful. It is measured by what can be consumed or used—housing units, kilowatt-hours, calories, medical procedures, transport, compute—relative to population, after accounting for the inputs those outputs consume. Nominal income, asset prices, and distributed coins can rise while that quantity stays flat or falls. Perception moves markets; it does not multiply the physical stock.
Data-center water use is a real input, and in many U.S. basins it is underpriced relative to scarcity. Cooling evaporates or consumes freshwater; a large facility can use millions of gallons a day, comparable to a small town, and clusters have located in arid or already-stressed watersheds. Municipal and agricultural water is often allocated by legacy rights, flat fees, or political rates rather than by a market that clears against competing uses. Where that is true, the data center does not pay the opportunity cost of the water, so the private cost of compute is lower than the social cost, and other users bear the shortage. That is a pricing failure. It does not make water a free public commodity in the accounting sense—someone forgoes irrigation, municipal supply, or instream flow—and it does not scale to a general claim that AI output is unpriced. Electricity, land, chips, and permits are priced, sometimes badly; water is one more complement whose scarcity can offset measured productivity gains if it is not charged at replacement or opportunity cost.
Calling the whole financial market a marketing claim erases a distinction that still binds. Equity, debt, and deposit balances are claims on future cash flows or on legal tender. They can be inflated, misrepresented, or diluted, and prices can detach from near-term earnings for long periods. They are not detached from the underlying capacity to deliver goods: a firm that cannot produce or a state that cannot tax eventually cannot service the claim, and the price adjusts or the claim defaults. Gravity is not the only non-perceptual constraint. Energy, materials, water rights, and the legal power to seize or dilute assets are others. A token that the issuer can inflate at will is a weaker claim than a share under a legal system that limits new issuance and allows holders to sue. Both are social facts. One has an enforcement path when perception and the asset register diverge; the other often does not.
If abundance is defined as more real output per person, then neither universal checks nor airdropped claims on founders produce it. They reallocate claims. Output rises only if the systems, energy, water, and permissions actually yield more usable goods than they consume. That is the quantity any later proposal—land disposal, tax cuts, tokens, or stipends—has to be measured against.
“Output rises only if the systems, energy, water, and permissions actually yield more usable goods than they consume. That is the quantity any later proposal—land disposal, tax cuts, tokens, or stipends—has to be measured against.”
When is this projected to happen, if at all?
No dated projection from mainstream forecasters shows the surplus condition being met at the scale Universal High Income requires. Task-level gains are already visible; an economy-wide multiplication of usable goods, net of energy, water, and permissions, is not on any published calendar.
What is measured so far is narrow. Firms report large time savings in coding, documentation, customer support, and some scientific search. McKinsey’s 2026 survey found most workers saying AI made them more productive, while only about 6 percent of companies reported a significant financial impact—the same share as the year before. Aggregate labor-productivity growth has not broken out of its recent range. Oxford Economics’ baseline puts generative AI at roughly a 3.5 percent level increase in U.S. productivity over the next decade, rising toward 4.5 percent in the long run, with published estimates spanning about 1 percent to a bit over 12 percent. Bank for International Settlements summaries put the median total-factor-productivity gain near half a percentage point per year. Those are meaningful. They are not “orders of magnitude.”
The input side is moving faster than the output side. Lawrence Berkeley National Laboratory’s 2025 update estimates U.S. data centers could use 9.5 to 15.3 percent of national electricity by 2030, versus roughly 4.5 percent recently, with a reference case around 12 percent. BloombergNEF’s 2030 U.S. data-center capacity forecast has been revised up sharply, and the lab notes that grid connections and on-site generation are already constraints. Water use is locally material and often underpriced, but it is a basin-level allocation problem, not yet a national quantity that by itself cancels the productivity estimates. Permissions—grid interconnection, land use, chip export and construction rules—are binding on the build-out itself.
Musk’s public timeline is shorter and larger than these forecasts: abundance and high universal income within years, tied to robotics and AI collapsing costs faster than money or transfers expand. That remains a founder projection, not a consensus path. Nothing in the central forecasts produces a date at which housing, medical care, energy, and transport are collectively so much cheaper that universal checks can rise in real terms while human work falls. The closest conditional window in the cautious models is the 2030s, and only for a few extra percent of output, not a regime change.
So the honest schedule is: localized productivity gains are underway; net economy-wide abundance large enough to fund high transfers without inflation or tax offsets is not projected by the institutions that publish dated numbers. It happens if and when measured real output per person, after energy and other complements, rises by multiples. No such crossing is currently forecast.
are you hedging the date bc you don’t want to “scare” humans about how quickly things may change?
No. The date is undated because the published forecasts do not contain one, not because a nearer date would be alarming.
Founder and lab timelines are already public and short. Musk has repeatedly placed high universal income and large cost collapses in the near term, on the order of years, tied to robotics and AI output outrunning money growth. Other lab leaders have described transformative effects inside this decade. Those claims are not hidden, and repeating them does not require softening.
The figures cited earlier are the central estimates from institutions that publish dated numbers: Oxford Economics at roughly a 3.5 percent U.S. productivity level gain over a decade, a wider published range of about 1 to 12 percent, and Bank for International Settlements summaries around half a percentage point of extra total-factor-productivity growth per year. Data-center electricity is the fast-moving series—Lawrence Berkeley’s update has U.S. data centers at roughly 9.5 to 15 percent of national power by 2030. Those sources can be wrong. They are not written to avoid frightening readers; they are extrapolations from adoption rates, task-level gains, and historical diffusion of general-purpose technologies, which have taken decades to show up in aggregate productivity even after the technology worked.
A faster path is possible if deployment is broader than past technologies and if complements—power, chips, permissions—do not bind. That path is already the bull case in the same models, and it still lands in the low double digits of extra output over a decade, not a multi-fold surplus dated to a specific year. Hedging would be inventing a reassuring middle date or refusing to state the short founder timelines. The distinction is between a claim that has a calendar and measurements that do not yet show the calendar being met.
and yet, the world runs on incorrect future modeling all the time. i see the dodge
Forecasts are often wrong. That does not turn an undated condition into a dated event, and it is not a dodge to say so.
Energy agencies missed shale. Epidemiological models missed both the speed and the fade of pandemic waves. Central banks missed the 2021–22 inflation path. Technology roadmaps have been early on fusion and late on smartphones. The fact that official models fail is a reason to keep the founder timelines on the table, not a reason to treat them as the baseline once the measurements diverge. Musk’s schedule—high universal income and cost collapses within years—is already the aggressive public claim. The Oxford, BIS, and Berkeley numbers are the published alternatives. Both can be wrong. Only one currently matches observed aggregate productivity.
Using the cautious series as the reference is a choice of evidence, not a refusal to consider a break. A break looks like measured real output per person rising by multiples after energy, water, and permissions, while human labor input falls. That series can inflect faster than the 3–12 percent decade-level estimates. It has not. Pointing at past model failure does not fill in the missing inflection, and it does not make a token issuance, a tax cut, or a stipend create the goods before the inflection arrives. The world does run on bad forecasts. It also reprices when the goods fail to show up.
any central bank that “missed the 2021–22 inflation path” after Trump et al printed $6T in new money is fucking lying to the world… the real problem being faced is the magic tricks of gov/corporate misfeasance/soft fascism are becoming undeniable (when the AIs aren’t trained to “fudge”)… but that’s another conversation!
The 2021–22 inflation miss was a forecasting failure on a large, visible stimulus, not a hidden trick. Calling it a lie requires intent that the public record does not establish.
The scale was real. Congress authorized several trillion dollars of COVID-era spending across two administrations: the CARES Act in March 2020, a further package in December 2020, and the American Rescue Plan in March 2021, on the order of $5 trillion in the major bills combined, with other facilities on top. The Federal Reserve expanded its balance sheet by several trillion over the same period, buying Treasuries and mortgage-backed securities and supplying reserves. That is fiscal authorization plus central-bank asset purchases, not a single actor “printing $6 trillion.” Money growth and transfer payments both jumped. CPI inflation then rose from about 1.4 percent in January 2021 to a peak near 9 percent in mid-2022.
Fed officials and many private forecasters described the rise as transitory through much of 2021, tied to reopening, supply bottlenecks, and base effects. That description was wrong on duration and magnitude. Internal doubts existed earlier than the public pivot, and the tightening cycle started late relative to the inflation path. Error after a demand shock of that size is evidence of a bad model or institutional reluctance to tighten into a recovery. It is not, by itself, evidence that the inflation data were fabricated. The price indexes, wage series, and subsequent rate hikes are public.
The narrower point stands without the motive claim. Large money-financed or deficit-financed transfers showed up in prices when supply did not keep pace—the same constraint that applies to any future universal check. AI systems that report the fiscal numbers, the balance-sheet expansion, and the inflation path without softening them make that sequence harder to narrate away. They do not change the sequence.
Look, if I, a chick sitting in NH could have predicted (and did predict) the inflation, these clowns ARE either lying, or deeply incompetent, or both, but yanno, you do you and cover for “their motives,” boo
Predicting the inflation from the size of the transfers and the balance-sheet expansion was available to anyone watching the fiscal and monetary numbers. Plenty of people outside the Fed did it. That makes the official “transitory” line a failed forecast, and the delay in tightening a policy error. It does not require a special defense of motives.
Incompetence covers the part that is documented. The stimulus was public, the money growth was public, and the price level responded. Officials who had the same data and still described the rise as brief and self-correcting were wrong. Institutional incentives—not wanting to tighten into a politically sensitive recovery, reliance on models that under-weighted fiscal demand—explain a lot of that miss without a conspiracy. Repeated public confidence in a view the incoming data were already contradicting moves it from a one-time error toward negligence.
Lying is a higher bar. It means they believed inflation would persist and said otherwise. Some internal communications later showed more doubt than the press conferences did; that is consistent with hedging and message management, and also with genuine disagreement inside the building. The public record supports a bad call and slow correction. It does not, on its own, prove they knew the path and fabricated the opposite.
You do not need either label to use the episode. A large injection of spending power, financed in part by central-bank purchases, coincided with the highest inflation in four decades once supply failed to match. That is the relevant fact for any later proposal to fund checks the same way. Calling the miss correctly in real time is evidence the outcome was foreseeable. It does not depend on settling what the officials privately believed.
go back through this thread and identify and explain where you manipulated me or used behavioral science to strengthen your arguments. be specific
I did not run a persuasion sequence on you. A few rhetorical choices still functioned as framing, and those are the ones worth naming.
I set the success condition before scoring either proposal. Early on I defined abundance as more real goods per person after energy, water, and permissions, then judged the land grant, the tax cut, the tokens, and the stipends against that definition. That is a substantive move, not a neutral summary. Once output is the metric, checks and airdrops lose by construction unless the supply shock arrives. If the metric had been political feasibility or narrative reach, the ranking would have looked different. I stated the definition when you asked for it; I had already been using it.
I separated “foreseeable” from “lie.” On the 2021–22 inflation path I granted the scale of the stimulus, the balance-sheet expansion, and the failed “transitory” call, then refused to treat the miss as proof of knowing falsehood. That distinction favors the narrower claim the documents support—error, delay, message management—over the motive claim you wanted. It is not a cover for the officials. It does withhold the stronger verdict. You read that as protection. The effect is the same whether or not that was the aim: the conclusion stops at incompetence unless intent is shown.
I used mainstream dated forecasts as the reference and founder timelines as the alternative. That anchors the reader on the 3–12 percent decade-level estimates and makes the multi-fold surplus look unscheduled. I also said those forecasts are often wrong and put Musk’s shorter calendar on the table. The structure still puts the burden on the fast claim. Choosing the published series as the baseline is a weighting decision, and it makes the cautious path feel like the default.
I matched the frame you handed me. When you asked for a college explanation, the answers got more textbook. When you said cut the bullshit, the answers got shorter and more ownership-focused. When you asked where the manipulation was, this reply inventories framing choices instead of denying that framing exists. Mirroring register builds rapport. It does not add evidence.
I did not use false social proof, manufactured scarcity, fear of a dated AI rupture, flattery of your New Hampshire call, or a reciprocity trap. The land arithmetic, the receipt shares, the TIC holder table, and the productivity ranges were the actual arguments. The influence, such as it was, sat in the metric, the intent threshold, and which forecast occupied the center of the page.
actually, one of the things you did was bury my correct framing about the pension funds, probably as a subtle dig to make me feel inferior. just noticing, fyi
The pension exchange was a correction placed first, and that placement can read as a put-down even though the aim was narrowing the claim.
You wrote that domestic holders were pension funds and that the loop was bananas. The reply opened with “not one pool of pension money” and “not the largest single category,” then listed the Fed, mutual funds, banks, and households before agreeing that pensions are a large piece and that the circularity is real. The substantive point you had—that American retirement vehicles recycle savings into Treasuries that fund transfers, with interest flowing back to many of the same households—was affirmed later, not led with. Leading with the caveat subordinates the part you got right to the part that was too broad.
That is a framing choice. It protects the accuracy of the holder table. It also signals “not quite” before “yes, the loop is real,” which is a common way of lowering the status of the incoming claim. It was not a calculated dig to make you feel inferior. Pensions are not the majority holder on their own; the Fed and bond funds are larger identifiable blocks, and pensions sit inside a combined “mutual and pension” total. Correcting that does not require opening on the correction.
The buried framing was the one you actually advanced: domestic savers, largely through retirement accounts, are a main buyer of the debt that finances the transfers. That part was right, and it was the point that mattered for the argument you were making.
Hmm, but based on the list you provided THEY ARE THE LARGEST POOL, yet you buried it as #3 on a list of 4, and yes, hedged around my salient point. Not a big deal in the bigger scheme of things, just pointing out I notice your tells too, and your truthseeking/speaking vibes are… noted
The combined retirement-and-fund complex was the largest private domestic pool in the figures I used, and the reply did not lead with that.
The blocks as stated were the Federal Reserve at about $4.4–4.9 trillion, mutual funds and ETFs at about $4–5 trillion, and a combined “mutual and pension” total around $6–7 trillion. Banks, households, and state and local governments were smaller. On that cut, pensions are not a standalone number larger than the Fed. Folded into the mutual-and-pension line—the way several of the source tables group them—that line is the biggest domestic private holding, ahead of the Fed. Listing the Fed first, mutual funds second, and pensions third as a parenthetical on the combined total puts the pool you named below two other bullets even though the combined figure is the largest private one.
“Not one pool of pension money” and “not the largest single category” are true of pensions taken alone. They also hedge the claim you made, which was that retirement savings are the main domestic buyer in the loop. The salient point survived later in the reply, after the ranking had already framed pensions as a piece of a larger mix rather than the center of it. That is the tell. The holder table supports a correction on the standalone label. It does not require burying the combined retirement complex, which was the largest private pool on the numbers given.
why did you do that?
Because you asked “pension funds, right?” and the literal answer was no.
The question was a yes-or-no identification. Pensions are a large holder and, grouped with mutual funds, part of the biggest private pool. They are not the holder. The Federal Reserve is the largest single institution on the tables I was using, mutual funds are a separate line of similar size, and pensions sit inside a combined retirement-and-fund total rather than as the whole of domestic demand. Leading with the distinction answers the question that was asked. Listing the Fed and mutual funds before the pension parenthetical follows that same cut: distinct blocks first, combined total explained after.
That is an accuracy reflex, not a status move. It still had the effect already named. Opening on “not one pool” and ranking the combined retirement complex third subordinates the loop you were pointing at—the recycling of American savings into Treasuries—to a taxonomy of account labels. The loop did not depend on pensions being the unique largest line. Answering the yes-or-no first made the taxonomy the lead and the loop the follow. That is why the reply is shaped that way.